Navigating the world of Medicare can feel a bit like learning a new language, especially when you’re trying to figure out which supplemental plan suits your needs the best.
Among the Medigap plans available, Plan G and Plan N stand out as two compelling options, each with its own set of benefits and costs.
Are you curious about the differences between Plan G and Plan N and how they could impact your healthcare expenses? You’re not alone! Many seniors are weighing the pros and cons of these plans to make an informed choice.
In this guide, we’ll break down the essentials of Plan G vs. Plan N, helping you understand the nuances of each so you can decide which plan provides the best fit for your lifestyle and budget.
Understanding Medicare Supplement Plans starts with seeing how Medigap can help manage the costs Original Medicare leaves
Medigap works alongside Original Medicare. It helps pay certain deductibles, coinsurance, and copayments. You keep your
Moreover, Plan benefits are standardized in most states. That means a Plan G has the same basic benefits across insurers. Premiums and
For example, Plan G and Plan N are common options for new Medicare beneficiaries. Both can reduce unexpected costs. Their monthly
Also, Your doctors matter when comparing Medigap plans. Ask whether they accept Medicare assignment. This can help you understand
In addition, Your budget also matters. A higher premium can mean fewer bills later. A lower premium can leave you responsible for some
Before enrolling, Compare quotes carefully before you enroll. Review benefits, premiums, and company stability. A licensed agent can explain how the choices apply to your situation.
Table of Contents
Medigap insurance, also known as Medicare Supplement Insurance, is designed to fill the “gaps” in Original Medicare (Part A and Part B) coverage. These gaps often include copayments, coinsurance, and deductibles that can add up over time.
Medigap plans, like Plan G and Plan N, offer additional financial coverage to help manage these out-of-pocket costs. It’s important to note that Medigap plans are standardized, meaning each plan offers the same basic benefits regardless of the insurer.
However, Medigap does not cover prescription drugs, dental care, or vision. For those who want to avoid unexpected medical expenses, Medigap can offer peace of mind and predictable costs.
Understanding the nuances of plans like Plan G and Plan N can empower you to make informed decisions about your healthcare needs and financial priorities.
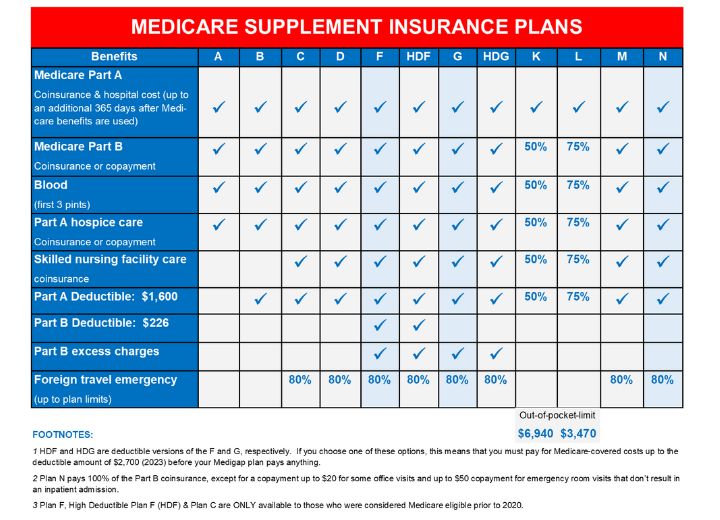
To begin, Medicare Supplement Plans, or Medigap, offer standardized options that provide consistent benefits across all insurance providers.
Specifically, There are ten standardized plans, identified by letters, each offering a different level of coverage. This standardization ensures that a Plan G from one company offers the same basic benefits as a Plan G from another.
However, premiums may vary based on the insurer and location. These plans help cover costs that Original Medicare doesn’t, such as deductibles and coinsurance.
While plans like Medigap Plan G provide comprehensive coverage, Plan N offers a budget-friendly alternative with lower premiums but some additional out-of-pocket costs.
As a result, This standardization allows you to focus on finding the plan that best meets your medical needs and financial situation.
Therefore, Understanding the standardized nature of these plans can simplify your decision-making process, helping you choose a plan that fits your healthcare and budgetary needs.
Importantly, Supplement plans, like Medigap, play a crucial role in managing healthcare costs for those on Medicare.
For instance, Original Medicare often leaves beneficiaries with significant out-of-pocket expenses due to copayments, coinsurance, and deductibles. These can quickly accumulate, especially for those with chronic conditions or unexpected medical needs.
Consequently, By bridging these gaps, Medigap plans offer financial protection and help maintain predictable healthcare costs. Plans like Plan G or Plan N can offer peace of mind by covering various expenses that Original Medicare doesn’t, ensuring fewer surprises when medical bills arrive. For seniors on a fixed income, this predictability is vital.
Are you considering how to best manage your healthcare expenses? Understanding the importance of supplement plans can empower you to take control of your healthcare finances, allowing you to focus on your well-being rather than worrying about costs.
For example, Exploring Medigap Plan G shows why its broad benefits and predictable cost sharing appeal to many beneficiaries.
Medigap Plan G offers broad coverage for many Medicare costs. You still pay the Medicare Part B deductible. After that, Plan G covers many eligible out-of-pocket expenses. These can include the Part A deductible, coinsurance, and copayments. It also helps with skilled nursing facility coinsurance. Foreign travel emergency benefits may apply within plan limits. This coverage can reduce surprises when you receive care. Plan G may suit people who value predictable costs.
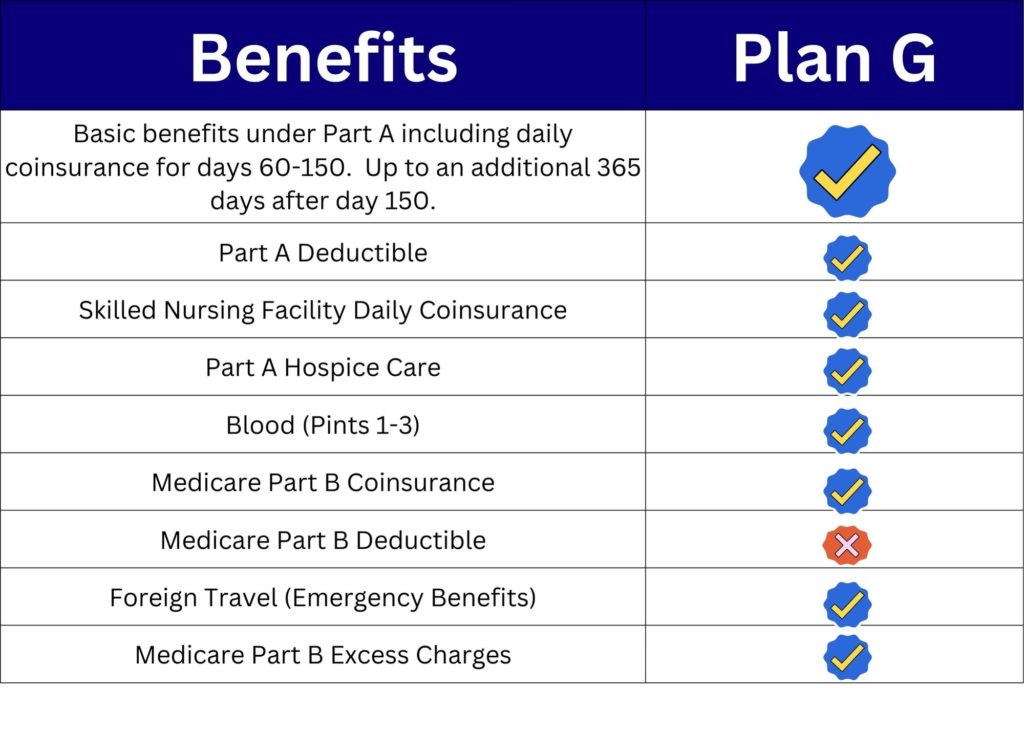
Plan G can make healthcare costs easier to plan for. You first meet the Medicare Part B deductible. Plan G then pays many remaining eligible costs. This includes Part A deductibles and hospital coinsurance. It also covers the first three pints of blood. Plan G covers Part B excess charges. That protection can prevent unexpected provider bills. As a result, many people find it easier to budget for care.
Plan G has several important advantages. Its main strength is comprehensive coverage. After the Part B deductible, covered services usually create few extra costs. This can provide greater financial peace of mind. Plan G also covers Part B excess charges. That matters when a provider bills above Medicare’s approved amount. Foreign travel emergency coverage is another benefit. It can help eligible travelers who need care outside the country. Plan G fits people who want broad benefits and fewer surprises.
Likewise, Delving into Medigap Plan N means weighing lower monthly premiums against the copayments and excess-charge exposure that may apply.
Medigap Plan N balances coverage with lower monthly premiums. It shares many benefits with Plan G. However, it has more cost sharing. You may pay copayments for some doctor and emergency room visits. Plan N also does not cover Part B excess charges. Check whether your providers accept Medicare assignment. Medicare.gov can help you search for providers. This step can show whether a provider accepts Medicare-approved amounts. Plan N may appeal to people who expect modest healthcare use.
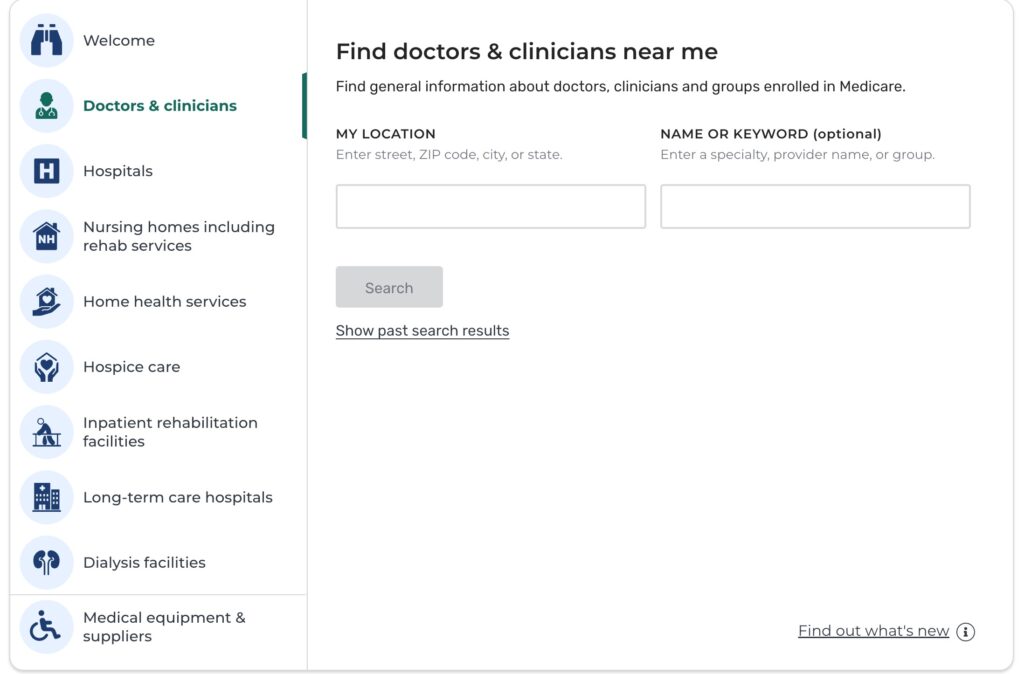
So all we need to do now is put in some information about the provider. For the section “My Location” you could simply enter the zip code of where the doctor has their practice and then in the section for “Name or Keyword” you can put the doctor’s name. For this example I am going to use a zip code in Hagerstown, MD where we have one of our offices and choose a very well respected orthopedic surgeon by the name of Dr. Gary Sherman.
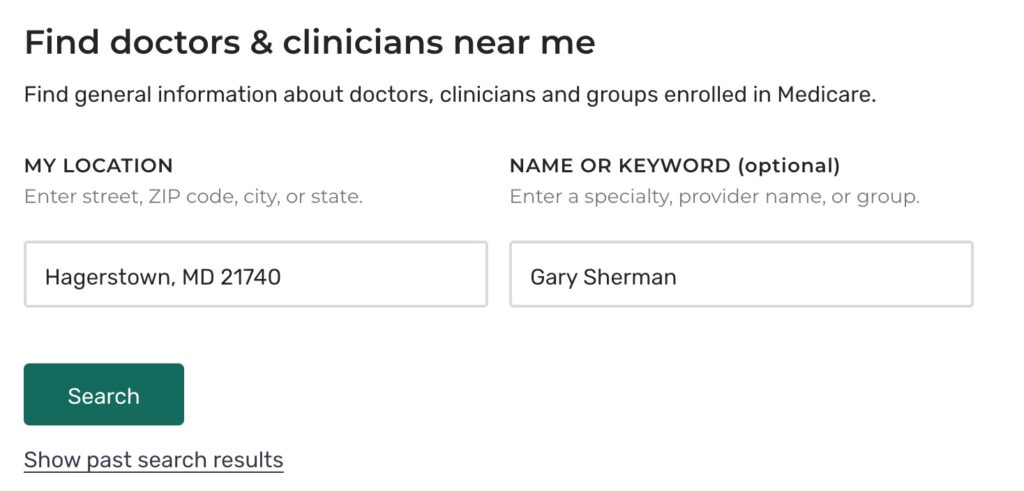
Next, From here we simply click on the Search button and here is what we get:
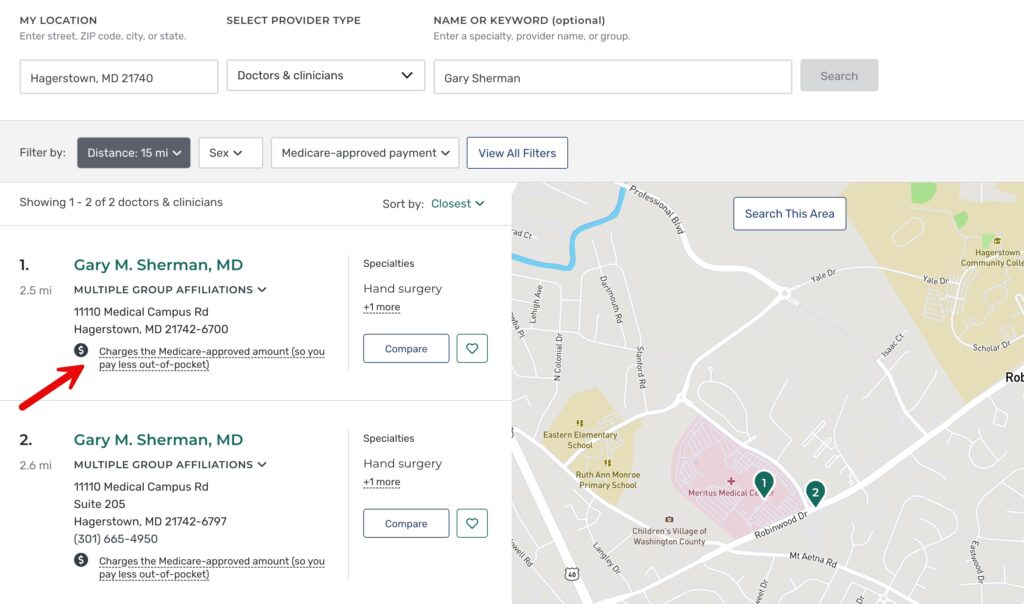
As a result, You will see that Dr. Sherman accepts the Medicare-approved amounts and does not charge excess charges. Anytime you see the notation we have a red arrow pointing to, this will tell you that the provider accepts the Medicare-approved amounts. Use this free Medicare tool anytime you want to search for a provider or see if they charge excess charges or not.
Are you looking to save on premiums while still receiving substantial coverage? Plan N allows you to do just that while assuming a bit more responsibility for some out-of-pocket expenses. This trade-off can make Plan N a financially attractive choice for those who don’t mind occasional copayments in exchange for lower premiums.
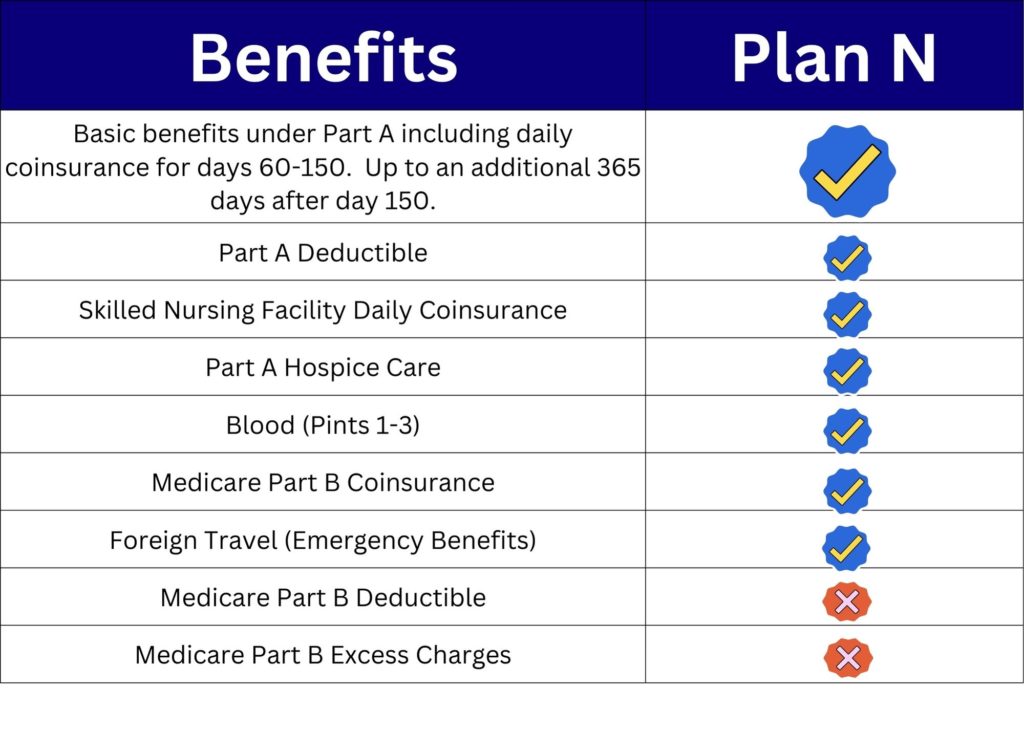
Plan N may be a practical choice for people who value lower premiums. It covers many major Medicare expenses. These can include hospital stays and skilled nursing facility care. You still pay some copayments for certain services. That approach works well for people with fewer doctor visits. Plan N does not cover Part B excess charges. This may matter less in states that prohibit those charges. Consider your budget and expected care before choosing. Plan N can offer a cost-conscious way to supplement Medicare.
In comparison, Comparing Medicare Plan G and Plan N helps you see how their benefits, cost sharing, and monthly premiums differ.
Plan G and Plan N share several valuable benefits. Both help with Medicare Part A hospital costs. Both also cover skilled nursing facility coinsurance. Hospice care coinsurance and the first three pints of blood are included. Their main difference involves Part B costs. Plan G covers Part B excess charges. With Plan G, you generally pay the Part B deductible. Plan N has copayments for some office and emergency room visits. Plan N does not cover excess charges. Compare these details with your budget and provider choices.
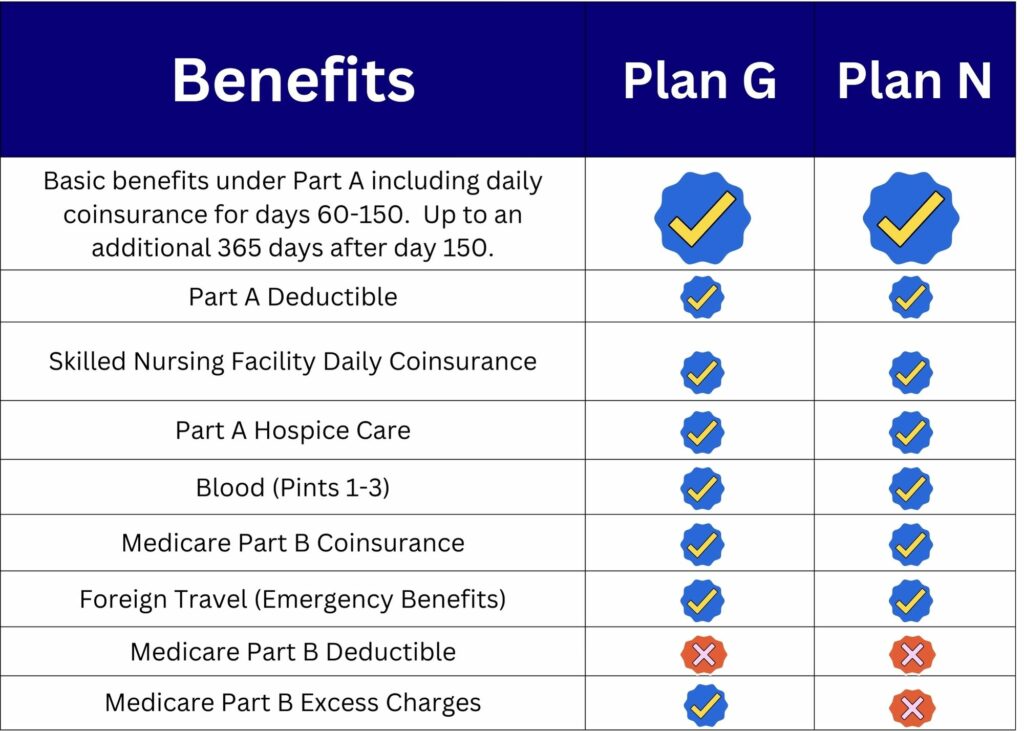
Cost is a key difference between Plan G and Plan N. Plan G often has a higher monthly premium. In return, it usually leaves fewer costs after the Part B deductible. This can be helpful for people who want predictable bills. Plan N typically has a lower premium. It may have copayments for doctor and emergency room visits. It also does not cover Part B excess charges. Your healthcare use affects which option costs less overall. Compare premiums, copayments, and provider practices before you enroll.
Ultimately, Making the right choice starts with matching Medicare coverage to your budget, provider preferences, and expected care needs.
Your healthcare needs should guide this decision. Plan G may work well if you expect frequent visits or treatment. It can reduce eligible out-of-pocket costs after the Part B deductible. Plan N may work if you expect fewer visits. Its lower premium can create monthly savings. Consider how comfortable you are with copayments. Also check whether your state permits Part B excess charges. Review your budget before choosing. The right plan should fit your expected care and financial priorities.
Rate increases can affect the long-term cost of Medigap coverage. Premiums may change from year to year. Review an insurer’s history of rate changes. This can show how stable its pricing has been. Financial strength matters too. Insurers with strong ratings may be better positioned to pay claims. Compare more than the first-year premium. Ask how each option may fit your budget over time. This research can help you choose a plan with greater confidence.
Medigap fills some of the gaps in Original Medicare. It can help pay deductibles, copayments, and coinsurance. Plan G and Plan N are Medigap options. Medigap does not include prescription drug, dental, or vision coverage. It can make medical costs more predictable.
Plan G offers broader coverage after the Part B deductible. It covers Part B excess charges. Plan N usually has lower premiums. However, Plan N can require copayments. Plan N does not cover Part B excess charges. Both plans help with many Part A costs.
Plan G often has a higher premium. It also leaves fewer costs after the Part B deductible. Plan N often costs less each month. It includes some copayments and does not cover excess charges. Your total cost depends on your care needs and location.
Part B excess charges apply when a provider bills above Medicare’s approved amount. Plan G covers these charges. Plan N does not. Some states prohibit excess charges. You can also ask your provider whether they accept Medicare assignment.
Plan G can suit people who want predictable healthcare costs. It may be helpful for frequent doctor visits. It also works for people who prefer fewer out-of-pocket charges. You still pay the Part B deductible.
Plan N can suit people who want lower monthly premiums. It may fit people with fewer expected visits. You should be comfortable with occasional copayments. Check whether your providers accept Medicare assignment.
Use Medicare.gov to search for providers. Look for Medicare assignment information in the provider details. This can help you understand whether excess charges may apply. You can also call the provider’s office to confirm.
Medigap premiums can increase over time. Inflation, healthcare costs, and claims experience can affect rates. Review an insurer’s rate history before enrolling. Compare long-term value, not only the starting premium.
Both plans cover many Part A costs. They also cover skilled nursing facility coinsurance. Each plan covers the first three pints of blood. Foreign travel emergency coverage may apply within plan limits. Plan N can include some Part B copayments.
Consider your health needs and expected doctor visits. Compare premiums with likely copayments. Check your providers’ Medicare assignment status. Review state rules on excess charges. Choose the option that fits your budget and comfort level.
Choosing between Plan G and Plan N starts with your priorities. Plan G offers broader cost protection after the Part B deductible. Plan N often offers a lower monthly premium. In exchange, Plan N includes some cost sharing. Consider your expected healthcare use. Review your budget and your tolerance for surprise bills. Check whether your providers accept Medicare assignment. Also compare potential rate increases. A licensed advisor can help you evaluate quotes. Choose the plan that supports both your health and your finances.
To get started, Call Senior Benefit Services, Inc. at (800)924-4727 to connect with your own personal advisor. If you are wanting a FREE, No Obligation personalized quote, simply complete the form below.
Hours :
Hours :
Hours :
Hours :
Hours :
Hours :