The 2027 Part D changes will reshape prescription drug coverage for millions of Medicare beneficiaries. Before Open Enrollment begins, you need to understand how these updates affect your costs. If you rely on a standalone drug plan or Medicare Advantage, these shifts will directly impact your wallet and your healthcare strategy.
The team at Senior Benefit Services, Inc. has decades of experience helping residents navigate these exact shifts. Here is a breakdown of the critical 2027 Part D changes and what you need to do to protect your coverage.
To understand how your costs are shifting, it helps to look behind the scenes. In recent years, the government created a temporary premium stabilization program. It provided financial support to insurance companies to limit how quickly plan premiums could increase.
However, CMS (Centers for Medicare & Medicaid Services) has announced that this temporary subsidy program will end on December 31, 2026. Without that federal safety net, insurance carriers will adjust their pricing to reflect true market conditions for 2027.
Because the temporary premium subsidies are ending, consumers with standalone Part D plans should expect higher monthly premiums in 2027. CMS predicts the average increase could be less than $10 a month. However, individual rate jumps will vary based on your insurance company, your plan, and where you live.
In 2025, Medicare introduced a prescription drug spending cap starting at $2,000. In 2026, that cap increased to $2,100. For 2027, the Part D annual out-of-pocket threshold rises again to $2,400 per year.
This means someone on expensive medications could pay up to $300 more next year. Once you reach the $2,400 cap, you do not pay anything else for covered medications for the rest of the calendar year. Keep in mind that premiums and medications not on your plan’s formulary do not count toward this cap.
Financial pressures on insurance companies are causing major disruptions in the Medicare Advantage market. When a carrier decides a plan is no longer profitable, it may shrink doctor networks, raise copays, or cancel the plan entirely.
Standard Medigap Plan G rates are rising significantly in many parts of the country. As a result, beneficiaries are looking for creative ways to keep comprehensive coverage while controlling costs.
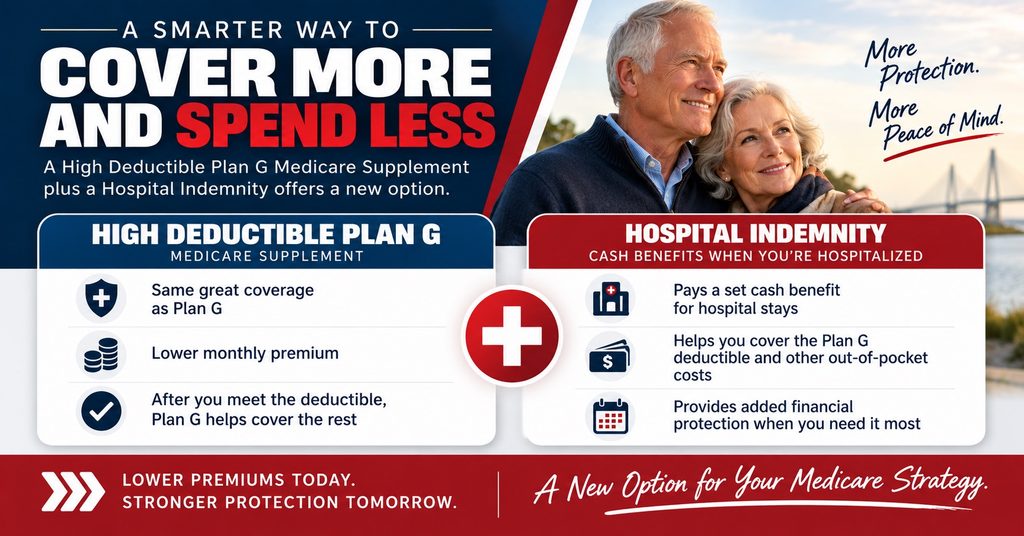
One emerging strategy for 2027 is pairing a High-Deductible Plan G with a hospital indemnity or cancer plan. These ancillary plans pay a direct cash benefit to help cover the higher deductible. At the same time, you lock in a much lower monthly Medigap premium.
Do not let your current plan automatically renew without reviewing your options.
Do not navigate the 2027 Part D changes alone. Contact Senior Benefit Services, Inc. today to schedule your free Open Enrollment review.
The Medicare Part D annual out-of-pocket spending cap is increasing to $2,400 in 2027. Once you spend $2,400 on covered medications, your plan covers 100% of covered drug costs for the rest of the year. Monthly premiums and drugs not on your plan’s formulary do not count toward this cap.
Yes, many standalone Part D premiums are expected to increase. The federal Premium Stabilization Demonstration ends on December 31, 2026. Insurance carriers will adjust 2027 pricing to reflect true market conditions. CMS expects average increases to stay under $10 a month. However, some carriers will raise premiums substantially on certain plans. Compare your overall costs for 2027 carefully.
Do not focus only on the plan premium. Instead, check what tier your medication falls into and how much the co-pay is. Look at your total out-of-pocket expense for the full year of 2027.
If a Medicare Advantage plan is terminated, you return to traditional Medicare Parts A and B. You receive a 63-day Guaranteed Issue Right. This lets you purchase certain Medigap policies without medical underwriting. Some carriers may also crosswalk you to a similar plan automatically.
Some beneficiaries are pairing a High-Deductible Plan G with a hospital indemnity or cancer policy. This secures a much lower monthly premium. The ancillary plan pays a direct cash benefit to help cover the deductible during a medical event.
Hours :
Hours :
Hours :